What does retirement planning for teens look like?
Retirement planning for teens can include setting long-term goals, saving part of earned income when the budget allows and learning how time may help savings grow. Teens with taxable compensation may also be eligible to contribute to an IRA, subject to IRS rules.
When should teens start saving for retirement?
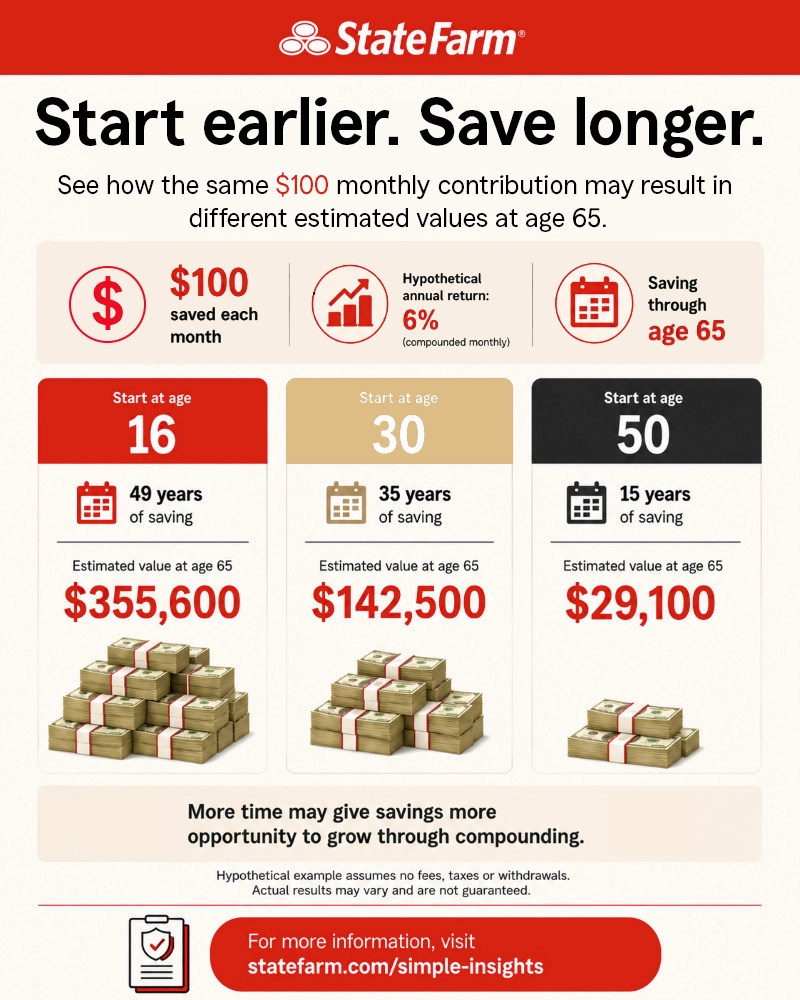
Teens can start when they have money available and saving fits their budget. Starting earlier may give retirement savings more time to grow through compounding, but returns are not guaranteed. Compounding happens when earnings remain in an account and may generate additional earnings over time. Retirement account values can rise or fall based on performance and investment choices.
A retirement savings calculator can help teens and families compare different starting ages, contribution amounts and assumed rates of return.
The infographic above shows how different starting ages may affect potential retirement savings when the contribution amount and other assumptions remain consistent.

Retirement savings for teens at a glance
Use this quick guide to see when teens can start saving, why starting early may help and when a Roth IRA may be an option.
When can teens start planning and saving for retirement?
Teens can start planning at any age and save when they have money available and room in their budget
Why might starting early help?
More time may allow earnings to generate additional earnings through compounding
How much should a teen save?
There is no single amount that fits every teen
Can a teen contribute to a Roth IRA?
A teen with taxable compensation may qualify, subject to current IRS rules
Does a minor need an adult to open a Roth IRA?
An account provider may require an adult custodian to open and manage the account
How to start retirement planning as a teen
Retirement planning for teens does not have to begin with a large contribution. Consider these steps:
- Track income and spending: Write down money from part-time work, tips or side jobs, along with regular expenses. A basic money management plan for teens can help show how much may be available to save.
- Set goals by time frame: List current needs, goals for the next few years and goals that are decades away. Retirement may be one of several long-term financial goals for high school students, along with education, training or future housing.
- Choose an amount that fits: A teen might start with a fixed dollar amount or a percentage of each paycheck. The amount should leave room for current expenses and other savings needs.
- Keep short- and long-term savings separate: Money needed soon may fit better in an accessible savings account. Retirement accounts can have tax rules and possible penalties for withdrawals, so they may be more appropriate for money that can remain saved for a long time.
- Review available account options: Compare retirement account types, eligibility rules, fees, withdrawal rules and other account features.
As income and expenses change, teens can revisit their plan and decide whether to adjust the amount they save. The broader steps for how to save for retirement may become more useful as a teen moves into full-time work.
Can a teenager open a Roth IRA?
Yes. Federal rules do not set a minimum age for contributing to a Roth IRA. A teenager may contribute if they have taxable compensation and meet current income and contribution rules.
The maximum contribution is generally the smaller of:
- The annual IRA limit: this amount may change from year to year
- Taxable compensation: the amount the teen earned during that tax year
Roth IRA income limits and contributions to other IRAs may further reduce the amount a teen can contribute.
Compensation generally includes wages, salaries, tips, commissions and net self-employment income. Income from babysitting, lawn care or another side job may count as taxable compensation if it is taxable self-employment income. Teens and families may want to keep records of income and related expenses.
A Roth IRA opened for a child or teen follows the same federal tax rules as other Roth IRAs. If the teen is a minor, an account provider may require an adult custodian to open and manage the account.
Roth IRA contributions are not deductible on a federal income tax return. Qualified Roth IRA distributions generally are free from federal income tax. Other withdrawals may be taxable or subject to an additional tax, depending on the circumstances. Teens and families may want to review current IRS rules and account details before taking money out.
Frequently asked questions
Can a teen save for retirement without a full-time job?
Yes. A teen can save money without a full-time job. To contribute to an IRA, the teen generally needs taxable compensation, which may include part-time wages, tips or qualifying net self-employment income.
Does an allowance count as compensation for a Roth IRA?
An ordinary allowance or gift generally does not count as compensation for an IRA. Payment for actual work may count if it is treated and reported as taxable compensation. A tax professional can help explain how the rules may apply.
Can a parent help fund a teen’s Roth IRA?
A parent may be able to provide money for a contribution, but the teen still needs taxable compensation at least equal to the contribution. The annual IRA limit and other eligibility rules also apply.
Should a teen save for college or retirement first?
There is not one answer for every teen. Consider education costs, transportation, emergency savings, current expenses and available income. Keeping separate goals may help a teen decide how much to direct toward each one.
Teens and families can use the retirement savings calculator to explore different starting ages, contribution amounts and assumed rates of return. A State Farm agent can help educate about available savings options, while a tax professional can help with personal tax questions.
This content was developed with the help of AI and reviewed by State Farm editors.
The information in this article was obtained from various sources not associated with State Farm® (including State Farm Mutual Automobile Insurance Company and its subsidiaries and affiliates). While we believe it to be reliable and accurate, we do not warrant the accuracy or reliability of the information. State Farm is not responsible for, and does not endorse or approve, either implicitly or explicitly, the content of any third-party sites that might be hyperlinked from this page. The information is not intended to replace manuals, instructions or information provided by a manufacturer or the advice of a qualified professional, or to affect coverage under any applicable insurance policy. These suggestions are not a complete list of every loss control measure. State Farm makes no guarantees of results from use of this information.
Neither State Farm nor its agents provide tax or legal advice.