11.02.2026
Understanding the Issues in Illinois
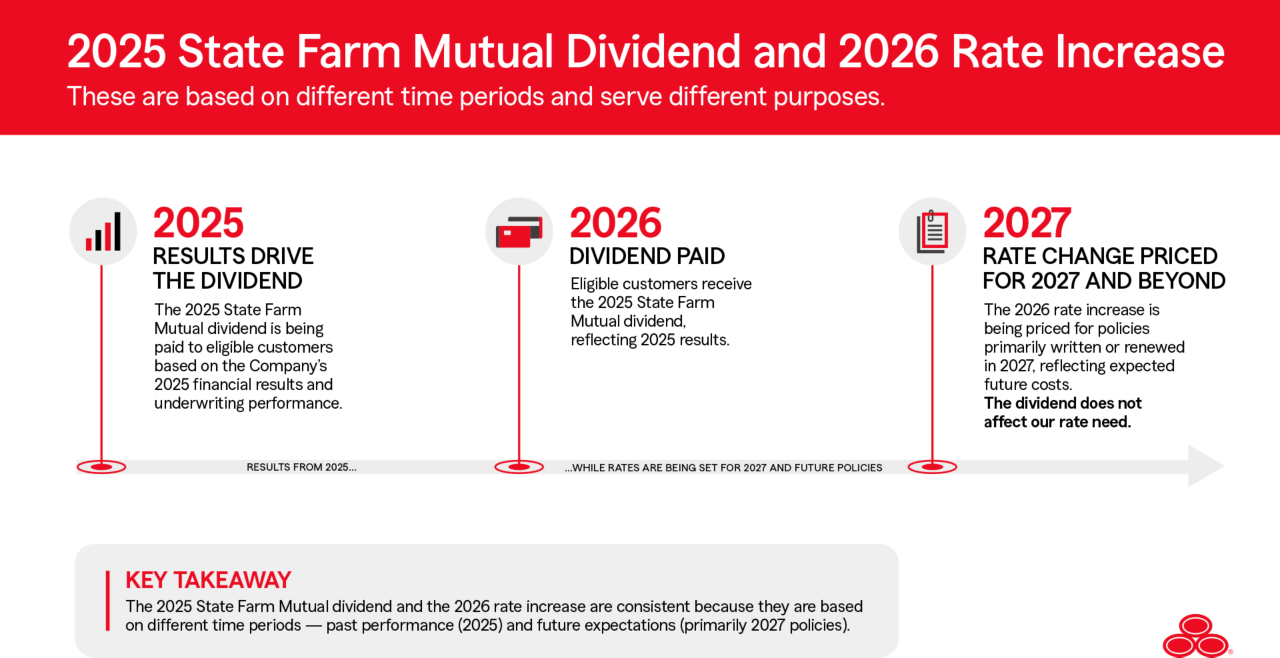
Auto Insurance Rates in Illinois: Expected Future Costs Versus Past Financial Results
At State Farm, we understand that the price of insurance matters to our customers, especially as families continue to manage rising household expenses. We also recognize that an auto insurance rate increase may be frustrating or confusing, particularly after recent rate decreases and the announcement of a dividend for eligible State Farm Mutual auto customers.
We want customers to understand why these decisions can happen at the same time and what they mean for their insurance costs.
Insurance rates are reviewed regularly and reflect the expected future claims costs and expenses of insurers. Rate increases and decreases are based on a variety of factors and trends, such as repair and rebuilding costs, labor costs, weather patterns, legal system abuse, and more.
The 2025 dividend recently issued for eligible State Farm Mutual Automobile Insurance Company policyholders was based on past company results and is one way State Farm returns value to our customers.
A dividend and a rate adjustment serve different purposes. State Farm Mutual issued a dividend based on past financial results. An auto insurance rate adjustment, on the other hand, looks ahead at expected future claims costs and expenses in a particular state. This means State Farm can return value to customers based on past results while also adjusting rates to reflect anticipated future claims costs and expenses in Illinois.
Several factors can influence the cost of auto insurance in Illinois, including vehicle repairs, medical expenses, claims trends, severe weather and the rising costs associated with legal system abuse. These expenses don't always follow the same trends as general inflation, and conditions can vary significantly from state to state. That's why insurance rates are evaluated based on the specific expected future claims costs and expenses in Illinois, rather than national trends.
We know that even small rate adjustments can have a meaningful impact on household budgets. While an overall rate change may be announced for Illinois, not every customer's premium will change by the same amount. Individual premiums depend on several factors, including vehicles, drivers, location, driving history, selected coverages, deductibles, and available discounts.
Insurance rate adjustments are necessary to reflect expected future claims costs and expenses so an insurer can pay future claims and be there for its customers.
State Farm is also working with Illinois elected officials to reduce insurance costs by supporting “drivefulness” initiatives that can help prevent crashes while advocating for stronger protections against legal system abuse that drive unnecessary costs and higher premiums.
We're here to help you understand your options. If your premium changes, we encourage you to contact your State Farm agent to review your policy, explore available discounts and consider coverage or deductible options that may better fit your needs and budget.
At State Farm, our commitment remains the same: to provide customers with dependable coverage and personal service when they need it most.
State Farm actions, updates, and responses in Illinois
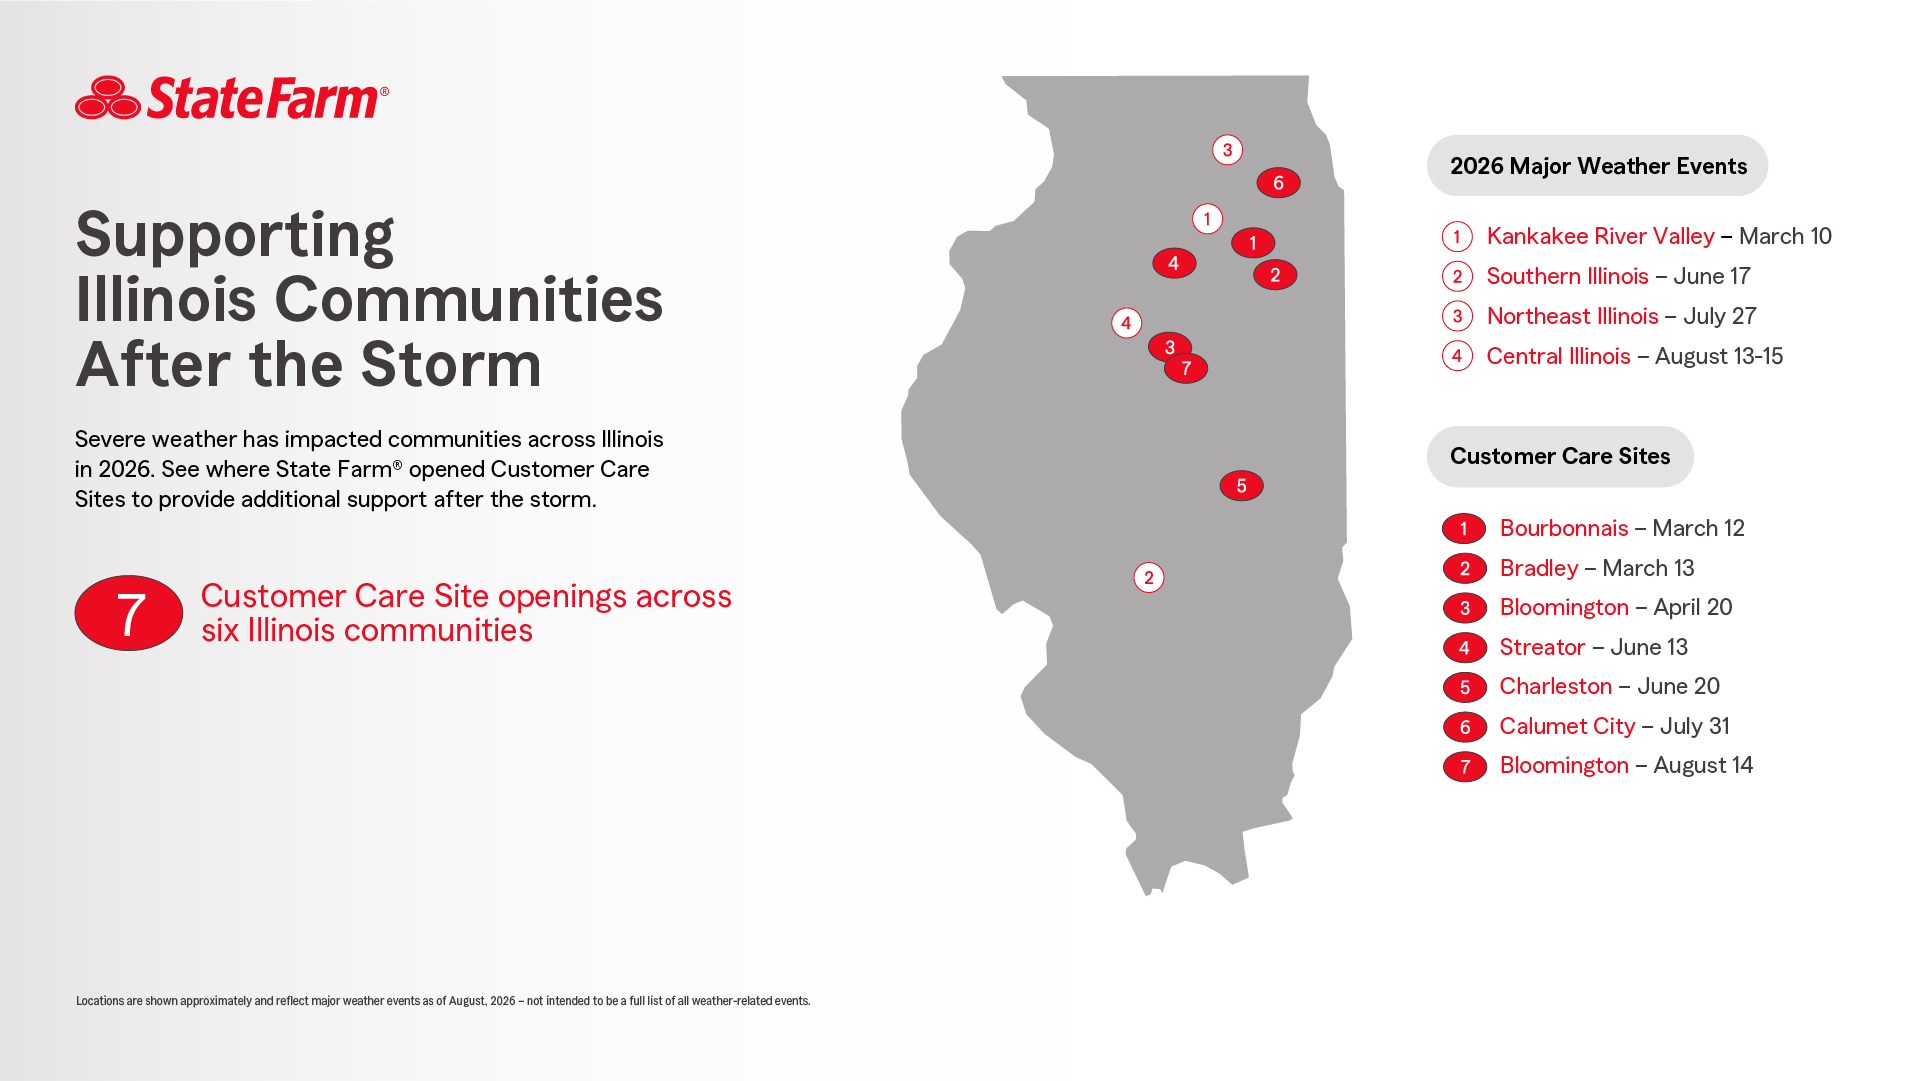
Illinois Weather and the Cost of Insurance
Illinois is experiencing an exceptionally active severe weather year. Through July, State Farm® customers in Illinois filed more home and auto catastrophe claims than customers in any other state, putting Illinois on pace for its highest catastrophe claim volume in a decade.
Illinois by the Numbers
- 96,000+ catastrophe weather-related home and auto claims in 2026
- Home catastrophe claims are 50% above the 10-year average
- Auto catastrophe claims are 100% above the 10-year average
- Illinois has recorded three consecutive years with more than 120 confirmed tornadoes
- As of August 19, 2026, Illinois surpassed 200 confirmed tornadoes this year.
As of July, State Farm has paid more than $799 million for storm-related losses in Illinois this year. For added context, in 2025 alone, State Farm paid $457 million in Illinois hail claims, third highest in the nation.
What Shapes the Cost of Homeowners Insurance
Illinois premiums are priced for the risk in this state – not for losses in other states. With decades of experience serving Illinois customers, State Farm draws on extensive data and expertise to understand how risks and costs are changing. We continuously review the latest information, so rates reflect the most current view of expected losses.
That means considering both the likelihood of covered losses and what those losses are expected to cost. We know affordability is a real concern for Illinois families, making it increasingly important to address the underlying factors driving those costs. Rising construction costs, severe weather, inflation and excessive litigation can all put pressure on the cost of insurance.
Our priority is being there for customers when the unexpected happens and helping them recover. That means staying financially prepared to pay claims as risks and costs change. Rates need to reflect the likelihood and expected cost of covered losses, but long-term affordability also depends on reducing the underlying risks and costs putting pressure on insurance. Illinois consumers deserve a strong insurance marketplace and meaningful progress on affordability. That means addressing the risks and cost drivers.
Work to be Done to Address Cost Drivers
State Farm will continue to engage with Illinois elected officials and advocate for a focused set of actions aimed at supporting a healthy insurance market and helping consumers navigate increasing severe-weather risks.
Priorities include advancing resiliency and home-hardening initiatives modeled on successful programs in other states; strengthening protections against post-storm predatory contractor solicitation and potential conflicts of interest involving public adjusters; and addressing legal system abuse that drives unnecessary litigation and increases costs for consumers through higher premiums.
With severe storms becoming a more prominent concern in Illinois, State Farm sees an opportunity to serve as a thought partner with lawmakers and regulators on solutions that strengthen resilience, support consumers and the broader insurance market, and help pull unnecessary costs out of insurance premiums.
Responding Today
When severe weather strikes, State Farm is there. Following late-July storms that brought nearly 100 mph winds, heavy rain and tornadoes to northern Illinois, State Farm deployed Catastrophe Claims Teams and opened a Customer Care Site in Calumet City. We welcomed elected leaders to the site to see State Farm doing what it does best – helping our customers recover.
Severe weather continued in August, generating another 2,000+ catastrophe claims in northern Illinois, followed by torrential rain and 70 mph straight-line winds in our Bloomington headquarters community. Throughout these events, State Farm Claims associates and agents have been helping customers navigate the recovery process.
Preparing for Tomorrow
Helping after a storm is only part of the equation. Long-term affordability also requires looking for ways to reduce damage before the next storm happens. That's why State Farm is investing in prevention as well as recovery.
At our Technology Research and Innovation Lab (TRAIL) in Bloomington, State Farm researchers study hail, wind and other threats and explore how stronger materials, construction practices and mitigation can better protect homes and communities.
Impact-resistant roofing is one practical way homeowners can make their homes more resilient and help reduce hail damage. When building, remodeling, or replacing a roof, homeowners can consider qualifying impact-resistant roofing materials. State Farm also offers premium discounts to eligible homeowners in many states with qualifying products.
State Farm works with the Insurance Institute for Business & Home Safety (IBHS) to advance research-backed approaches to stronger construction. Programs like FORTIFIED also demonstrate how homes can be built or retrofitted beyond standard construction practices to better withstand severe weather.
The research demonstrates how more durable construction and improved building standards can reduce damage, strengthen communities and potentially save lives.
Illinois families are already feeling the squeeze of high prices at the grocery store, gas pump, and yes, insurance costs. That’s why we’re concerned that the Illinois General Assembly’s two insurance bills—one for auto and one for homeowners—will add to that burden.
We’re focused on protecting customers and making sure any reforms strengthen affordability—so Illinois consumers aren’t the ones paying the price for rushed, one-size-fits-all policy changes.
Illinois’ current insurance market relies on data, risk modeling, and statistical analysis to keep rates fair, accurate, and sufficient to pay claims. We understand there’s a desire to address affordability for Illinoisans—but the legislation proposed will not deliver cost savings and may very well reduce competition for consumers.
Illinois Insurance Association Executive Director Kevin Martin reminded the General Assembly that the state has long benefited from one of the most competitive auto insurance markets in the country. He added, “A recent U.S. News & World Report study found that Illinois has the sixth-lowest auto insurance premiums in the nation – a ranking driven by strong competition, consumer choice and a regulatory framework that allows insurers to respond quickly to changing market conditions.”
The auto insurance legislation being debated in Springfield would upend this system by imposing a form of prior approval rate regulation that has failed consumers elsewhere.
We urge lawmakers to slow down, consider evidence-based approaches, and prioritize reforms that could actually improve affordability and strengthen consumer choice—not reduce it.
This Spring, the Illinois House passed an amended version of Senate Bill 1486. The bill must still get approval from the Senate and the Governor’s signature to become law. The current language in this bill would apply to both homeowners and auto policies. It would allow the Department of Insurance to order retroactive refunds. It would create an undefined filing standard, resulting in delayed rate implementation, reduced competition, and increased market instability.
State Farm has publicly shared, “We were disappointed by the outcome of the Illinois House vote on the amended SB 1486. This state has had the most competitive and stable insurance market in the country for more than 50 years. We believe this action will undermine auto and homeowners insurance rate predictability, market stability, and reduce competition while ultimately leading to higher insurance prices for Illinois residents.”
It is also important to note that State Farm has lowered auto insurance rates in 40 states over the past year, including Illinois. We are committed to continuing to work with lawmakers and the Department of Insurance on reasonable rate regulation legislation, and to support real solutions that tackle the root causes of rising homeowners insurance rates. State Farm is supportive of SB 3029 – the so-called storm chaser bill that has passed out of the Senate and is currently being considered in the House. The consumer-protection measure is aimed at contractors who show up after storms and pressure homeowners into signing repair contracts quickly.
Legislation that only targets pricing without addressing underlying factors like escalating storm losses, rising rebuilding costs, legal system abuse, and claim fraud will risk reducing competition and shrinking consumer options.
Auto insurance rates are falling in Illinois and many states across the country. In fact, State Farm has lowered rates twice in Illinois over the past year by a combined 15 percent on average (down 5.7% in July 2025 and down another 9.6% in December).
The homeowners market is less forgiving as severe weather, and inflationary pressures continue to increase costs for customers and insurers. So, some state lawmakers suggest changing home insurance rate regulation rules in Illinois could help. But it’s not that simple. State Farm believes HB3799 would undermine rate predictability, market stability, and reduce competition while ultimately leading to higher insurance prices for Illinois residents.
We know from our experience working in a variety of regulatory structures that more competition leads to more choice for consumers. And with more choice comes better products and better prices. That’s why the average homeowner insurance premium in Illinois is below the national average. And we hope to keep it that way.
State Farm is collaborating with lawmakers on a new bill that would give the department greater regulatory oversight in a more stable and predictable way than the current proposal. HB3799 lacks safeguards to prevent indefinite regulatory approvals and unpredictable retroactive refund demands. There are other, better options. Lawmakers can strengthen oversight without destabilizing the market.
Our focus remains on our customers and providing the best products at the lowest possible price. Unlike companies with shareholders, our goal is not to maximize profits but to earn enough to maintain financial strength that allows us to keep the promises we make.
State Farm complies with all applicable laws and remains committed to working with Illinois regulators. This Illinois taxpayer funded lawsuit is without merit and unrelated to State Farm’s Illinois rates or our Illinois customers.
State Farm has provided the Illinois Department of Insurance all data necessary to support its Illinois insurance rates.
State Farm will continue to proudly serve millions of people in Illinois and work with the Illinois Department of Insurance to benefit Illinois customers on behalf of the more than 21,000 agents, agent team members, and State Farm employees who call Illinois home.
Working with Illinois
State Farm continues to work with regulators and legislators in Illinois to help our customers.
- State Farm made a rate filing in early June 2025 indicating a Homeowners rate increase in Illinois. That filing was more than 32-pages long and is available publicly on the National Association of Insurance Commissioners (NAIC) SERFF site. It includes detailed actuarial analysis supporting the rate filing.
- On June 23, State Farm also submitted a 5-page response to questions the Department asked about the filing. No additional questions were received and the filing was closed out by the Department of Insurance on June 27.
- State Farm first learned of concerns with the rate filing through the Governor's press release in July. Since then, State Farm met with both the Director of the Illinois Department of Insurance and a Deputy Governor. There were no additional requests for information in that meeting.
- State Farm has provided the same type of information as other insurers provide in supporting rate filings in Illinois. Over the last three years, many insurers have raised Homeowners rates, citing deteriorating loss trends in Illinois; several of those increases in total exceed the State Farm increase.
- State Farm's retained counsel on these issues submitted a letter on July 31 to the Director of the Illinois of Department of Insurance clarifying our position and once again indicating our continued willingness to work with state officials.
- Unrelated to the June rate filing, the Illinois Department of Insurance in March 2024 demanded nationwide data of State Farm. This demand exceeds the legal authority of the Illinois Department of Insurance. State Farm has, therefore, not provided this data, but has asked the Illinois DOI to engage in a process that would allow an independent third-party/judge to resolve this dispute. State Farm made that request of the Department nearly one year ago.
An update to auto insurance rates
Auto insurance rates in Illinois will decrease an average of 5.7%, with some customers seeing reductions in premiums of up to 15%. Rate adjustments will apply to new and existing policies starting July 18, 2025. This decision is driven by trends projecting lower claims costs.
So, why are homeowner prices going up in Illinois?
Thank you for your trust in State Farm®. We understand no one likes to see their insurance rates increase, and we don’t take these decisions lightly. That’s why we want to provide you with some context around our approach in Illinois, where we are decreasing average auto insurance rates, and increasing average home insurance rates.
As a mutual company, State Farm is focused on serving its policyholders. Unlike companies with shareholders, our goal is not to maximize profits but to earn enough to maintain financial strength that allows us to keep the promises we make and to support future growth.
As we continue to adapt to changing conditions, we remain committed to providing you with the best possible value, service, and support. Thank you for allowing us to protect what matters most to you.
Home insurance rates are on the rise in Illinois due to rising home replacement costs and more frequent severe weather events that are driving up the cost and frequency of claims. These changes reflect broader trends in loss patterns and repair costs and are necessary to help ensure we can continue providing reliable coverage to our policyholders.
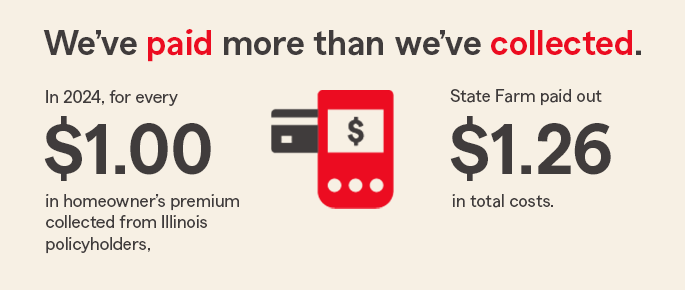
Home insurance claims costs are exceeding premiums collected. The cost of covering Illinois homeowners’ losses is exceeding the premiums we’re earning—an indication we need to adjust prices. Last year, those total costs amounted to $1.26 for every dollar in premium we collected. The year before, it was $1.30. Such losses are unsustainable.
Inflation matters. The costs of materials and labor have risen, affecting how much it costs to repair or rebuild homes. In the insurance business, the rates we charge are set in advance to cover potential future losses, including the costs to rebuild homes. As repair costs continue to rise, home insurance rates are as well.
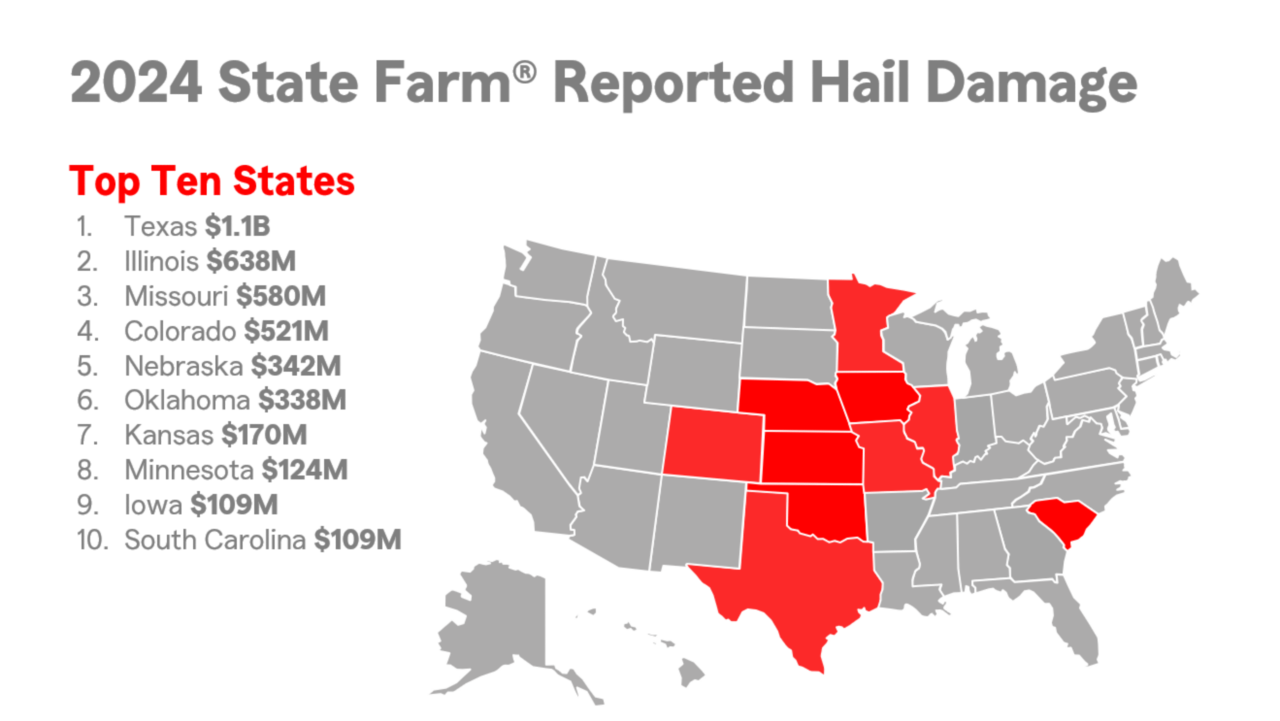
Severe weather—wind/hail and tornadoes—is increasing in Illinois. Trends in recent years indicate damaging storms are more frequent here. In fact, Illinois had more hail damage claims than any other state except Texas in 2024.
Illinois premiums are priced for the risk in this state—not for losses in other states, including wildfires, earthquakes, or hurricanes.
Contact your agent to discuss coverage options
State Farm is committed to being a responsible steward of the resources we manage, ensuring we can continue to provide the coverage you need in the face of increasing risks.
We encourage you to reach out to your State Farm agent to discuss your coverage options. Our team is here to help you navigate these changes and find the solutions that work best for you.
Wind and hail deductible explained…
One of the ways we are limiting rising premiums is through the introduction of a Wind/Hail Deductible. Illinois home insurance customers already choose deductibles related to loss perils. Illinois customers will now be required to have a minimum 1% Wind/Hail deductible as part of their home insurance policy. It will apply in instances where the cause of loss is deemed to be wind or hail. All other losses will be subject to the other deductible(s) stated within the policy.
Choosing a higher deductible is one way to reduce the premium you pay for insurance. Your State Farm agent can discuss options that are available.
Resources
-
Building Stronger Homes for Severe Weather - State Farm -
Data Shows Illinois Tornado, Hail Risk Rising – State Farm -
IBHS FORTIFIED Home -
Infographic: Illinois Homeowners’ Insurance: Affordable, Accessible, and Essential | III -
State Farm in Illinois Fact Sheet -
Hail Damage Increases in 2024: 5 tips to reduce it -
Impact-Resistant Roofing Material That Stands Up to Nature - State Farm -
Things to consider when replacing a roof -
Understanding wind mitigation and its benefits -
See if you are eligible for State Farm homeowner discounts -
Why are homeowners' insurance rates on the rise?
Illinois News Stories
-
The Daily Line: Affordable Insurance is at Risk in Illinois -
Crain's Chicago: Opinion: California-style insurance rules would backfire in Illinois -
Chicago Tribune: State Farm defends hefty 27.2% hike in Illinois homeowners insurance rates -
Fox Weather: Chicago leads nation in homes susceptible to severe weather damage -
Chicago Tribune: Illinois affected by record number of billion-dollar disasters -
Crain’s Chicago Business: Opinion: Insurance industry a bedrock of the Illinois economy -
WGLT: State Farm tests safety and durability of housing materials at TRAIL facility